The biomethane pricing gap
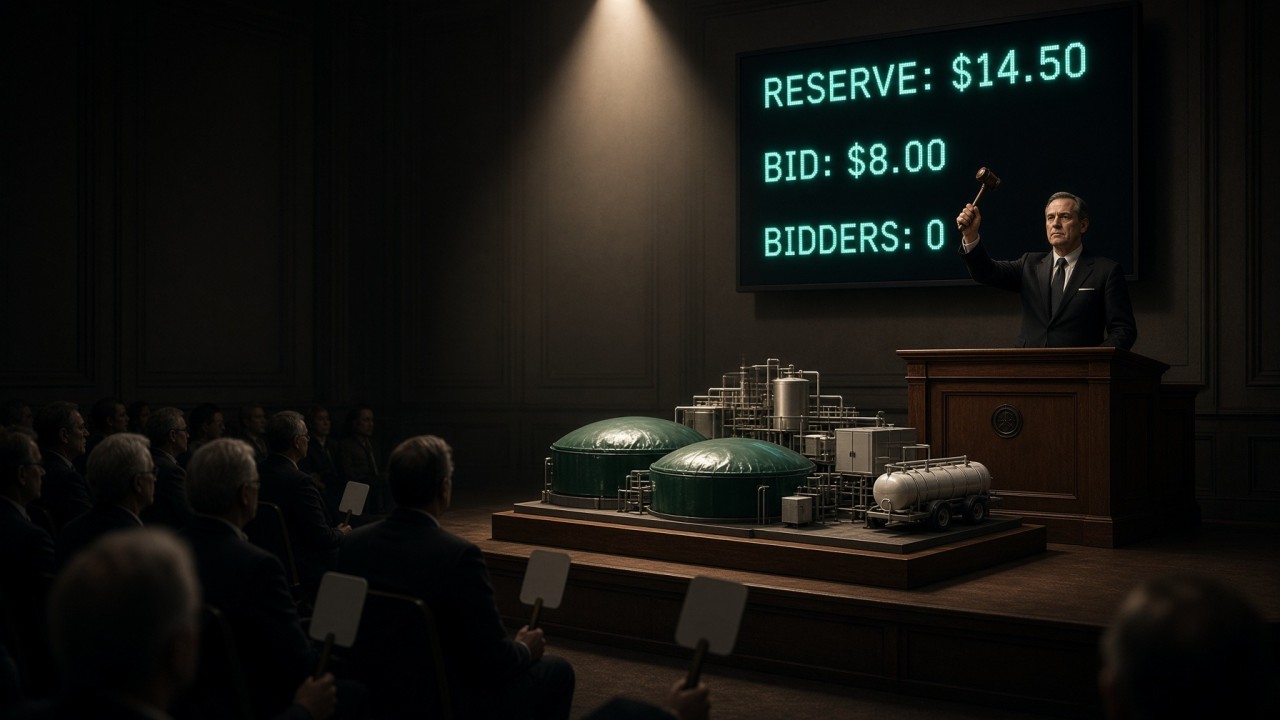
There is a simple reason the pipeline of palm oil mill effluent (POME) biomethane projects in Malaysia and Indonesia keeps stalling at the same point. It is not the technology, which is mature. It is not the feedstock, which is abundant. It is not the absence of policy ambition, of which there is plenty. It is price.
On my own numbers, a bankable POME biomethane project needs an offtake price in the region of US$14.5 per MMBtu to be financeable. The market pays around US$8. That gap — roughly US$6.5/MMBtu, or nearly double — is the whole story. Everything else is commentary.
Below is where the US$14.5 comes from, why the US$8 is not only low but is itself understated, and why the one revenue stream everyone reaches for to close the gap — carbon — is not available to close it.
Where US$14.5 comes from I want to be careful about this figure, because it is the number people will want to argue with.
US$14.5/MMBtu is my bankable estimate for an indicative greenfield case: a 60 tph mill, POME covered-lagoon capture, membrane upgrading to pipeline spec, compression and virtual-pipeline (tube-trailer) dispatch. It is built bottom-up from a real EPC bill of quantities and real equipment quotes, not from a brochure — capture and conditioning, gas pre- treatment and membrane upgrading, compression and dispatch, balance of plant, engineering and owner's costs, and contingency. On that basis the total installed capex lands near US$6.5 million, annual operating cost near US$0.84 million, and — levelised over a 15-year life at a 12% cost of capital, against a realistic output of about 123,000 MMBtu per year — the required price works out to roughly US$14.5/MMBtu.
The important word is indicative. That number will move with project location, the specific end use, technology selection, the cost of finance, the interest rate environment, opex assumptions, and a dozen other factors. A different developer with a cheaper feedstock position, owned trailers, a shorter haul to the injection point, or concessional capital will land somewhere else. Two levers dominate: the biogas capacity factor — real POME capture runs well below nameplate, and I use 0.75 — and virtual- pipeline transport cost, which is distance-driven.
So do not read US$14.5 as a constant. Read it as this: any honestly-built bankable estimate lands well north of US$8. Rework my inputs aggressively and you might reach US$12 or US$13. You are still stranded above the market. The argument does not depend on the decimal. It depends on the gap.
Why US$8 is low — and why even US$8 is understated Absent a separately-contracted green attribute, biomethane injected into the Malaysian grid clears at fossil commodity parity — that is, at the natural gas benchmark, which is anchored to the Malaysia Reference Price (MRP). In recent periods that has sat around US$7–8.5/MMBtu.
But there is a second squeeze hiding underneath the first, and it is worth naming. The MRP is defined as the weighted-average FOB price of LNG exported from Malaysia. It is, in other words, an export-gate realisation — lagged (PETRONAS applies a six-to-seven-month lag), oil-indexed, and built on a legacy contract portfolio.
In a separate analysis I published in July, I compared Malaysia's realised LNG export value against what Japan paid for comparable volumes over the same period. Using Department of Statistics Malaysia volumes and values, Malaysia realised about US$8.37/MMBtu FOB. Japan paid about US$11.61/MMBtu CIF. After applying a published shipping-cost proxy, the difference was roughly US$2.37/MMBtu. That is a benchmark comparison, not a proven loss — the two portfolios differ in contract duration, indexation, destination rights and much else — but the gap is persistent and it is large.
The consequence for biomethane is direct. The reference price a green molecule is measured against is an administered, export-derived number that empirically sits some US$2.37/MMBtu below premium-market realisation. So the developer is squeezed twice: first denied a green premium, and second benchmarked to a fossil reference that under- rewards even plain methane.
Decompose the gap and it looks like this. Floor US$14.5, market US$8, gap US$6.5. Of that, roughly US$2.4 is the reference price sitting below premium value, and the remaining ~US$3.8 is the genuine cost premium of building and running the plant — a premium that, today, has nowhere to land.
Why carbon cannot close the gap The instinctive fix is to stack carbon revenue on top of the gas price. POME methane is a potent greenhouse gas; capturing it instead of venting it from open lagoons is real abatement, and methane's warming potency makes that abatement valuable. Surely, the thinking goes, you sell the gas and sell the carbon, and the two together clear US$14.5.
You cannot, and the reason is structural rather than commercial.
When biomethane is sold as a certified low-carbon fuel — ISCC PLUS is the standard used in the Malaysian market — the methane-capture benefit is
baked into the fuel's carbon intensity. That is precisely what makes certified POME biomethane's gCO₂e/MJ so low. And that low-carbon- intensity attribute travels with the molecule to the buyer, who books it against their own Scope 1 or Scope 3 target. The carbon value has already been spent. It left with the gas.
Which means the producer cannot also issue a voluntary carbon credit for the same avoided methane. That is double counting — the same tonne of abatement claimed twice — and certification schemes and carbon registries prohibit it. So it is a hard either/or:
Sell certified gas, and the green value is embodied in the fuel and claimed by the buyer — and, on the evidence of the market's one disclosed certified deal, the certification and attribute are controlled midstream, not by the mill; or Sell carbon credits, in which case you can only sell the gas itself as plain, uncertified commodity gas — and the standalone credit route is doubly weak, because the voluntary price is thin and, where methane capture is increasingly required of new mills, the credits face an additionality problem that guts their value.
There is no third revenue line. That is why the gap is a structural fact and not a negotiating failure. You can be the best dealmaker in the industry and you still cannot conjure a stream that the accounting rules forbid.
What an underwater contract looks like This is not theoretical. Consider the flagship POME-biomethane project in the region that actually put numbers into the public domain — a mill- linked plant, a 15-year gas purchase agreement signed in 2019, a project value of about RM25 million, and a headline commitment to deliver a minimum of 250,000 MMBtu of biomethane a year into the grid.
The headline volume was never remotely achieved. On the revenue the operator disclosed in its own listing documents, the run-rate in the plant's first months implies output on the order of a quarter of that 250,000 MMBtu figure. The plant had been in commercial operation for roughly four months when it stopped supplying after an on-site incident, and the supply obligation was then suspended under an accepted force majeure. It is not my purpose here to relitigate that incident. The pricing point stands on its own: a project selling at commodity parity, against a build that needs far more, will under-deliver — because the contract was underwater from the first molecule. A 250,000 MMBtu promise priced near US$8 was never going to be a business.
What would actually move projects None of this says biomethane cannot work. It says the current price structure cannot finance it, and pretending otherwise produces exactly the outcome above.
Three things move the needle, and a bankable project generally needs at least one of them. A green premium the producer actually owns and can write into a long-dated offtake — not a premium captured midstream, and not a carbon credit the certified molecule has already precluded. Concessional or blended capital that lowers the annualised capital line, which is the single biggest component of the levelised price. Or a captive use case — diesel or LPG displacement inside the mill's own operations, priced against the fuel it replaces rather than against a depressed gas benchmark.
Absent one of those, the arithmetic does not change, and the pipeline stays where it is. The gap is not a detail to be negotiated away. It is the
reason.
Figures are indicative and drawn from my own project model, real EPC and equipment quotations, and public data. The LNG export-realisation comparison is set out in full in my July 2026 article, "Malaysia's LNG Export Realisation Compared with Japan's LNG Import Price," with primary sources (DOSM, PETRONAS MPM, World Bank, ACCC/FTI, Federal Reserve). This is market commentary, not investment advice.
Comments
No comments yet.