Without the IMO, FuelEU is engine noise
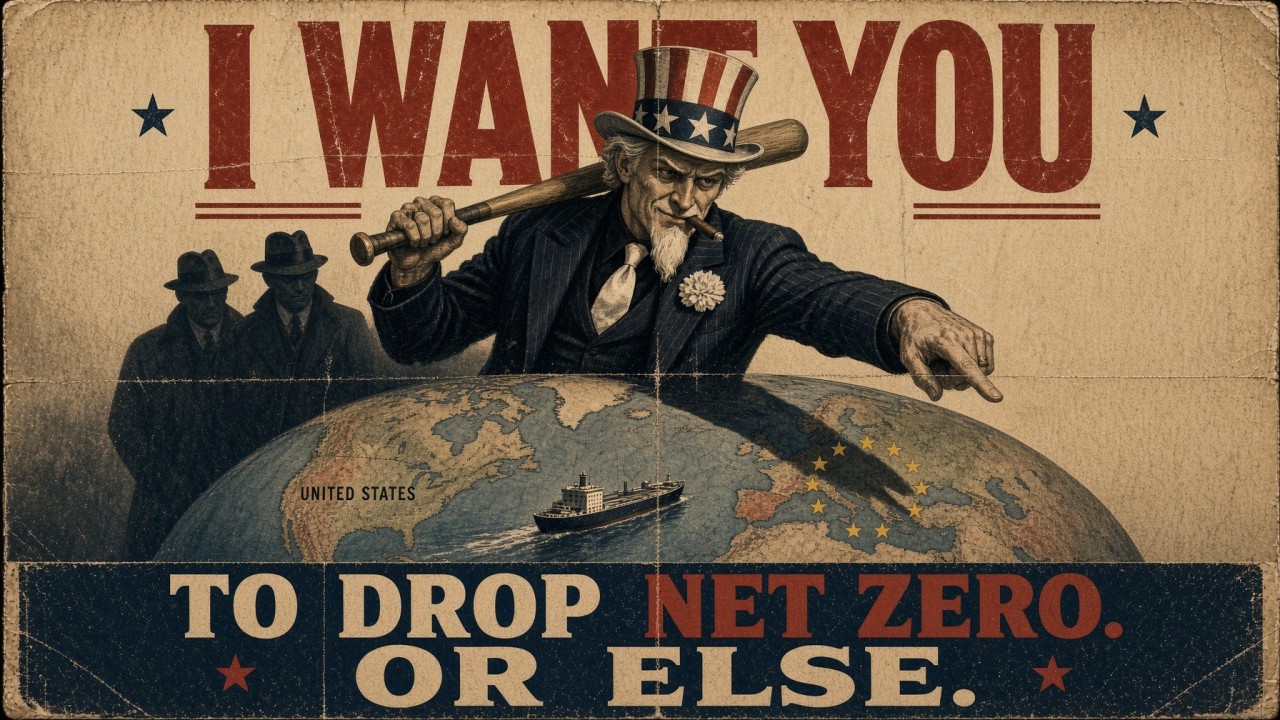
Fossil LNG passes, bio-LNG doesn't pay, and the global rule that would change both is being strong-armed off the table.
Fossil LNG already meets the EU's FuelEU Maritime target, on every engine until 2030 and on the best engines until 2040. That says more about the mandate than about the fuel. This article starts with bio-LNG: what it is worth to a shipowner once its emissions are counted on the same basis as fossil LNG. The answer is about half the emissions cut, about half the compliance value, and not enough to cover the cost. But the bigger problem is FuelEU itself, and the absence of the global IMO rule that was meant to sit behind it.
Bio-LNG is sold to shipowners as a near-zero emissions version of the fuel they already burn. On paper it is. The carbon in the methane was in the atmosphere beforehand, so FuelEU Maritime scores its combustion at zero. But combustion is not where the argument is won or lost. The emissions that matter sit either side of the tank, and they are easy to leave out.
The number to beat FuelEU puts fossil LNG at 76 to 89 g CO₂e per MJ, well to wake, depending on the engine. That figure already includes producing the gas, liquefying it, shipping it and bunkering it. A bio-LNG claim has to be measured against the same boundary. Once it is, three sources of fossil emissions come back in.
1. The power to make it Upgrading biogas to biomethane and then liquefying it takes about 1.5 to 2 kWh of electricity per kilogram of fuel. On a coal-heavy grid, at around
800 g CO₂/kWh, that alone adds about 25 g CO₂ per MJ. On a clean grid it adds about 2 g. For a plant that buys its power, the carbon intensity of the fuel is largely the carbon intensity of the grid.
2. The trucks that bring the feedstock in A digester beside a mill barely moves its feedstock. A liquefaction plant needs volume, and volume means a catchment. In a Southeast Asian network we modelled, 32 suppliers delivered about 3,600 tonnes of residue a day over an average one-way haul of 40 km. Collection and loading came to about 3.5 kg of CO₂ per tonne, almost all of it diesel. Lignocellulosic feedstock, digested at a measured 0.30 m³ of methane per kg of volatile solids, carries about 4,500 MJ of methane per wet tonne, so that haul adds about 0.8 g CO₂/MJ. Stretch the catchment to 150 km, which is where a plant ends up once the nearest suppliers are committed, and it is about 2.5 g. Wetter fibre, or trailers that fill by volume before they reach their weight limit, pushes it higher.
The diesel is the small part. The bigger issue is what scale does to the feedstock. The near-zero figures in the brochures usually rest on a methane-avoidance credit: manure or effluent that would otherwise have vented. At the volume a liquefaction plant needs, the next tonne is an energy crop, or a residue that was never going to emit methane, and there is no credit to claim. Even where the credit is real, the methane is not destroyed. It becomes the product. The carbon credit market is effectively meaningless at bio-LNG scale.
3. The trip from plant to ship Fossil LNG's 76 to 89 g already includes delivery to the ship. A bio-LNG figure that stops at the plant gate does not. Road tanker to port adds about 0.2 to 1 g/MJ, depending on distance. The bunker vessel, and often a sea leg, adds roughly another gram. Cryogenic tanks lose methane along the way, and the engine slips methane whether the gas came from a well or a digester. Scoring combustion at zero covers none of this.
Adding it up Grid, feedstock haul and delivery take a fuel sold as near zero to around 30 g CO₂e/MJ before it reaches the engine. With engine slip it lands at about 32 g on a low-slip diesel engine and about 46 g on an Otto medium- speed engine. Against 76 to 89 g for fossil LNG, that is a reduction of about 50 to 60%. Real, but not a replacement.
What that does to the price A shipowner pays for bio-LNG in two parts. The molecule is worth the same as fossil LNG, because it burns the same. On top of that, the owner will pay for the emissions it avoids, and no more. Under FuelEU, those avoided emissions have a price.
At 30 g upstream, bio-LNG avoids about 44 kg of CO₂e per GJ. What that is worth depends on what compliance costs:
• At the FuelEU penalty of about €640 per tonne, it is worth about €28 per GJ. A genuinely near-zero fuel would be worth about €46.
• At the pool price, which is what ships actually pay for compliance, it is worth about €5 per GJ. OceanScore's pool index fell from €225 per tonne in May to about €109 in September.
• The EU ETS adds about €4.50 per GJ, because biogenic CO₂ is not charged.
So the realistic premium over fossil LNG is about €9 per GJ. Making bio- LNG costs €17 to €30 per GJ more than fossil gas at normal European prices (Oxford Institute for Energy Studies cost data, gas at €8 to €11 per GJ). The premium covers the cost only if gas spikes or compliance trades near the penalty. The producer controls neither.
Three more things make it tighter.
First, most LNG-fuelled ships do not need bio-LNG yet. Fossil LNG already meets the FuelEU target for 2025 to 2029 on every engine. A low-slip diesel engine stays inside the target until 2040. An Otto medium-speed engine needs about an 8% blend to meet the 2030 target. Until the mid- 2030s, bio-LNG is mostly bought to generate surplus for pools, at pool prices.
Second, the threshold. FuelEU only recognises bio-LNG that meets the Renewable Energy Directive's greenhouse gas criteria. For a new plant that means at least 65% below a 94 g fossil comparator, or no more than about 33 g/MJ. At 30 g the fuel passes, with almost no headroom.
Third, the runway. FuelEU tightens every five years, to 62.9 g/MJ in 2040, 34.6 in 2045 and 18.2 in 2050. At 32 to 46 g, bio-LNG on its own misses the 2045 target on an Otto engine and the 2050 target on any engine. A ship ordered today will still be trading in 2050. Green methanol made from biomass, with a reduction in the order of 80 to 95%, lands at roughly 5 to 18 g/MJ and stays inside the targets to 2050. It has no methane slip, no cryogenic boil-off, and it moves at ambient temperature in ordinary tanks. For an owner choosing a fuel for the life of a ship, green methanol is the better insurance.
The bigger doubt: FuelEU itself All of this assumes FuelEU bites.
It covers all the energy used on voyages within the EU, but only half the energy on the leg between an EU port and the last or next port outside it. Voyages that never touch the EU are not covered at all. A ship from Asia that calls at a nearby non-EU port on its way in has only that final short leg counted, and only at half. Article 2(1)(d) of the Regulation is explicit: half the energy on voyages where "the previous or the next port of call" is outside the EU. Take a ship from China calling at Singapore, Colombo, Jeddah and Tanger Med before Rotterdam. Unless it is a container ship, only Tanger Med to Rotterdam counts, a few days of steaming out of several weeks, and only half of that. The anti-evasion list names two ports, Tanger Med and East Port Said, and applies only to container ships. The Commission proposed tightening it in July, but still around container transhipment.
Pooling does the rest. An operator can run its compliant ships on the EU- facing legs, and LNG ships already beat the target, then pool their surplus across the rest of the fleet. That is compliance by allocation, not by fuel. A pool price that has halved since May is consistent with a market long on paper surplus.
The IMO was meant to make this global. It has not. Adoption of the Net- Zero Framework was adjourned in October 2025, MEPC 84 did not approve it in May, and the next attempt is in December. The United States, now the world's largest LNG exporter with about a quarter of the global market, led the campaign that stalled it in October, with threats of
sanctions and tariffs against countries that supported it, and in March formally asked the IMO to drop it altogether. Threatening sanctions and tariffs to kill a vote at a UN body is not diplomacy. It is a mafia-style standover: nice treaty you have there, shame if something happened to it. It is not hard to see whose business it protects. Without a global rule, FuelEU remains a regional measure with a porous edge.
What would change it Not a better bio-LNG. Clean power at the plant, feedstock digested where it arises and low-slip engines would all make the fuel lower emmisions intensity. None of them creates a buyer. While only the last leg into Europe is counted, and only at half, compliance stays cheap, the pools stay long and the premium stays thin.
The only thing that would change it is a global rule. If the IMO adopts the Net-Zero Framework, emissions are priced on every voyage, not just the EU-facing slice, and a fuel's well-to-wake intensity counts across the whole life of the ship. That is when the gap between a 50% fuel and a 90% fuel becomes real money. Until then, the debate over bio-LNG, green methanol and FuelEU compliance is largely a fuss about nothing: a small share of shipping's fuel, priced at the margin.
Until the IMO acts, that version of bio-LNG is a smaller fossil fuel with a biological feedstock, sold into a market that barely needs it. It should be priced as one.
Sources • FuelEU Maritime, Regulation (EU) 2023/1805: Article 2(1)(d), Article 3(10) and 3(11), Annex II well-to-wake factors, recital 13.
• ClassNK, FAQs on the FuelEU Maritime, Q5 (port of call).
• OceanScore Pool-Price Index, May to September 2026.
• Oxford Institute for Energy Studies, NG203, Biomethane in Europe, January 2026.
• Directive (EU) 2018/2001 (RED II), Article 29(10).
• DNV, IMO MEPC 84: revisiting the Net-Zero Framework, 2026; National Law Review, MEPC 84 advances negotiations amid political headwinds, 2026.
• European Commission maritime ETS revision proposal, July 2026.
• ENGINE, LNG Bunker Snapshot, Rotterdam, 21 September 2026.
• OilPrice.com, How the US became the world's LNG superpower (US share of global LNG exports, 2025).
Comments
No comments yet.